infolinks

Sunday, April 13, 2014

Petronas Chemicals

Petronas Chemicals Group Berhad (Stock code 5183) was listed in BursaMalaysia on 26th November 2010. Its price performance in BursaMalaysia is not very spectacular with the closing price on 11 April 2014 at RM6.75. At this price the PE is 15.35 with a yield of about 3%. Earning per share for year ending 2010 is 40 sen, 2011 is 45 sen, 2012 is 31 sen and 2013 is 40 sen. Dividend per share paid for year ending 2010 is 19 sen, 2011 is 16 sen, 2012 is 22 sen and 2013 is 40 sen. So with that said, I can safely predict that this comnpany will remain profitable and will pay dividend in the coming year.

Petronas Gas (Stock code: 6033) close at RM23.98 on 11th April 2014. With this closing price PE is 32.97 and yield about 2%

Petronas Dagangan (Stock code: 5681) close at RM30.26 on 11th April 2014; with PE 35.92 and yield about 2% also.

Eventhough these 3 companies are in different business they are all GLC (Government Linked Company).

Petronas Chemicals is in the news recently. On 10th April 2014 the partnership with BASF to produce citral and its precursors becomes a reality and the joint investment is RM1.5 billion. I believe that this joint investment once come to fruition will be earning accretive, that is when it goes into production in 2016. It is still far away but this may prompt some long term investors to accumulate Petronas Chemicals shares.

Let us look at the technical aspect of this counter below.


 Looks like there is suppot at RM6.65 which is close to the 11th April 2014 closing. Does it sounds like accumulation opportunity , for long term I mean.

Look at the more recent chart.below.

 It has just pierce through the wedge and no volitality yet. I predict that its price  will move above RM6.75 soon and maybe it is good to buy some if your holding of Petronas Chemicals is still small.

Invest with responsibility and good luck.


Sunday, December 1, 2013

Warren Buffett still the best role model for any stock investor.


Rules That Warren Buffett Lives By
Warren Buffett is arguably the world's greatest stock investor. He's also a bit of a philosopher. He pares down his investment ideas into simple, memorable sound bites. Do you know what his homespun sayings really mean? Does his philosophy hold up in today's difficult environment? Find out below.

"Rule No. 1: Never Lose Money. Rule No. 2: Never Forget Rule No. 1."Buffett personally lost about $23 billion in the financial crisis of 2008, and his company, Berkshire Hathaway, lost its revered AAA ratings. So how can he tell us to never lose money? He's referring to the mindset of a sensible investor. Don't be frivolous. Don't gamble. Don't go into an investment with a cavalier attitude that it's OK to lose. Be informed. Do your homework. Buffett invests only in companies he thoroughly researches and understands. He doesn't go into an investment prepared to lose, and neither should you.

Buffett believes the most important quality for an investor is temperament, not intellect. A successful investor doesn't focus on being with or against the crowd.

The stock market will swing up and down. But in good times and bad, Buffett stays focused on his goals. So should we. (This esteemed investor rarely changes his long-term investing strategy no matter what the market does. Learn more in Warren Buffett's Bear Market Maneuvers.)

"If The Business Does Well, The Stock Eventually Follows.""The Intelligent Investor" by Benjamin Graham convinced Buffett that investing in a stock equates to owning a piece of the business. So when he searches for a stock to invest in, Buffett seeks out businesses that exhibit favorable long-term prospects. Does the company have a consistent operating history? Does it have a dominant business franchise? Is the business generating high and sustainable profit margins? If the company's share price is trading below expectations for its future growth, then it's a stock Buffett may want to own.

Buffett never buys anything unless he can write down his reasons why he'll pay a specific price per share for a particular company. Do you do the same? (They don't call him "The Oracle" for nothing. Learn how Buffett comes up with his winning picks; check out Think Like Warren Buffet.)

"It's Far Better To Buy A Wonderful Company At A Fair Price Than A Fair Company At A Wonderful Price."Buffett is a value investor who likes to buy quality stocks at rock-bottom prices. His real goal is to build more and more operating power for Berkshire Hathaway by owning stocks that will generate solid profits and capital appreciation for years to come. When the markets reeled during the recent financial crisis, Buffett was stockpiling great long-term investments by investing billions in names like General Electric and Goldman Sachs.

To pick stocks well, investors must set down criteria for uncovering good businesses, and stick to their discipline. You might, for example, seek companies that offer a durable product or service and also have solid operating earnings and the germ for future profits. You might establish a minimum market capitalization you're willing to accept, and a maximum P/E ratio or debt level. Finding the right company at the right price - with a margin for safety against unknown market risk - is the ultimate goal. (Learn about the different kinds of risk that investors must face in Risk And Diversification: Different Types Of Risk.)

Remember, the price you pay for a stock isn't the same as the value you get. Successful investors know the difference.

"Our Favorite Holding Period Is Forever."How long should you hold a stock? Buffett says if you don't feel comfortable owning a stock for 10 years, you shouldn't own it for 10 minutes. Even during the period he called the "Financial Pearl Harbor", Buffett loyally held on to the bulk of his portfolio.

Unless a company has suffered a sea change in prospects, such as impossible labor problems or product obsolescence, a long holding period will keep an investor from acting too human. That is, being too fearful or too greedy can cause investors to sell stocks at the bottom or buy at the peak - and destroy portfolio appreciation for the long run.

You may think the recent financial meltdown changed things, but don't be fooled: those unfussy sayings from the Oracle of Omaha still RULE!

The Bottom Line
Find out how he went from selling soft drinks to buying up companies and making billions of dollars; see Warren Buffett: The Road To Riches.

Wednesday, July 10, 2013

Bearish news article from Malaysia Chronicle


EDITOR'S PICK Malaysia’s current household debt problem is not the result of our government’s recent policies to encourage private expenditure. Actually, the current debt problem has been accumulating for the past 15 years. The history of Malaysia’s household debt can be traced back to 1997 when the household debt to GDP was only 39% then. This was also the year that Malaysia was struck by the Asian Financial crisis.
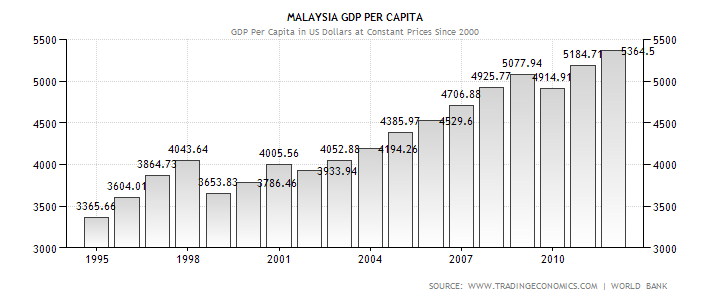
Since then, Malaysia embarked on an expansionary fiscal and monetary policy which led to an expansion of credit and also the proliferation public projects so as to extract its economy out of the recession. During the Asian Financial Crisis in 1999 Malaysia’s GDP per capita felled to $3653.83 compared to $4043.64 recorded in 1998. However since then as the expansionary policies worked its way into the economy, Malaysia’s GDP per capita risen as a result. This can be shown by the following graph on Malaysia’s GDP per capita since 1995.

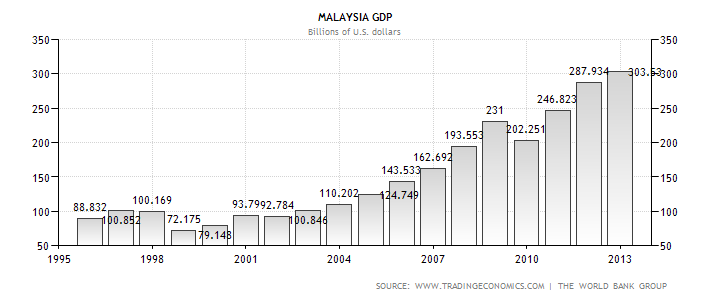
To encourage the private sector to spend, lending procedures are relaxed and interest rates are held low. As a result of the increases in both private and public expenditure, Malaysia’s GDP recorded a fourfold increase in 2012. In 1999, Malaysia’s GDP was valued at $72.175 billion and has since risen to $303.53 in 2012. This can be shown by the following chart.
However, the credit expansion brought about by our government earlier has led to a further increase in the household debt. As of 2010 Malaysia’s household to GDP debt has reached 78% where more than 55% of the loan concentration is in the mortgage market and 23% into the automotive market. And in 2012 the ratio went up to 83% which represents an increase of 13% from 2011.
Our next question is what contributed to our record Household Debt?
False Expectation of improved economic conditions brought about by our Government. We have mentioned many times in our previous articles that our Government has been painting a false picture on the real condition of our economy. With the aid of the media we are led to believed that our economy is growing at a healthy pace (GDP growth of 4.1%), our stock market is resilient, our housing market is healthy and sustainable (no bubble yet) due to the increasing rural to urban migration of the workforce and so on.
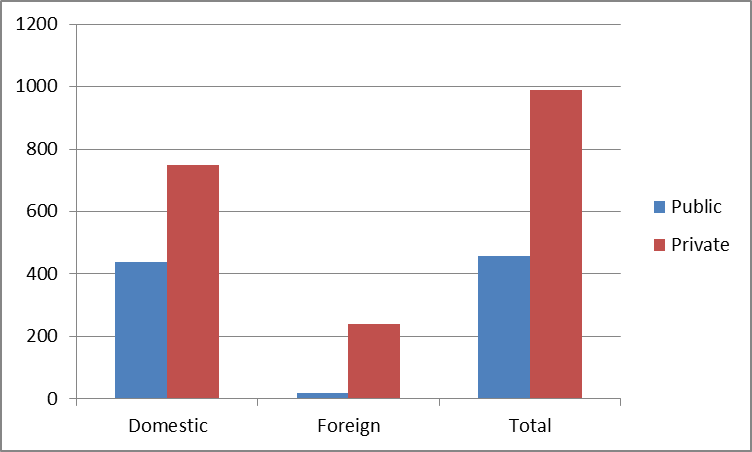
The easy availability of credit in the past and the lack of supervisory on the part of Bank Negara had led to an enormous build-up of the private sector debt. We shall present again the following chart which we have already mentioned in our last article titled ‘Is our GDP growth a Hoax?’
The following is the chart for the total debts by the private and Government sector as of 2011.
Debt
Domestic
Foreign
Total
Public
438
18
456
Private
749
239
988
Given the GDP of RM 860 billion we can then proceed to calculate the Debt/GDP ratio of both the public and private sector. The table below summarizes the ratio of domestic and foreign debts held by the public and private sector.
Debt
Domestic
Foreign
Total
Public
51%
2%
53%
Private
87%
28%
115%


From the above we can conclude that at the present moment the private sector poses a greater risk to financial default than the public sector. This is due to the fact that the private sector is much more exposed to any downside risk, arising not only from size of the debt (87%) but also its exposure to foreign debt (28%). Large exposure to foreign debt is risky because it is subjected to movements in foreign currency (US$ in this case) or external systemic market risk.
The movement of the US dollar creates currency risk or what we called ‘Foreign Exchange Exposure’ in Treasury terms. Foreign Exchange Exposure refers to the risk associated to a decline in a country’s currency. Currency depreciation can have the effect of reducing a company’s profits due to increased cost in imports or loss due to the higher repayments of loans denominated in US dollar.
How big a loss associated with currency movement depends on our Ringgit. On the negative node our country is currently running a ‘Twin Deficits’. Twin Deficits refers to a situation when we are having two economic problems at the same time (Budget Deficit + Balance of Trade Deficit). Twin deficits are known to create havoc in an economy by accelerating the decline of a country’s currency and in this case the Ringgit. So, obviously the risk of default in our private sector has certainly increased due to the problems coming in from multiple fronts.
A boom in the Housing and Stock Market. The boom in the housing and stock market for the past couple of years has increase the risk appetite of investors. Somehow they reckoned they have found a way to make money without putting much work. To them making money can be as easy as sitting in the stock market and pressing some buttons or flipping some real estates. Hence this led to many of them holding to a portfolio of 3 to 4 houses which risked being wipe-out should there be a serious downturn in the real estate market.
A strong response from the private sector especially from the business community to increase their exposure to debt due to the expectation of better times ahead.
Problem with ARMs Mortgage
Another problem we are facing is that about 80% of the loans given to the housing market are in the ARMs (Adjustable Rate Mortgages) category which is also known as ‘teaser loan’ in the U.S. To lure prospective borrowers, banks offered very low initial repayments (such as BLR – 2 to 4%) during the first 3-5 years. Once that duration expires or resets then borrowers will have to start paying higher mortgages. That’s where the nightmare comes in.
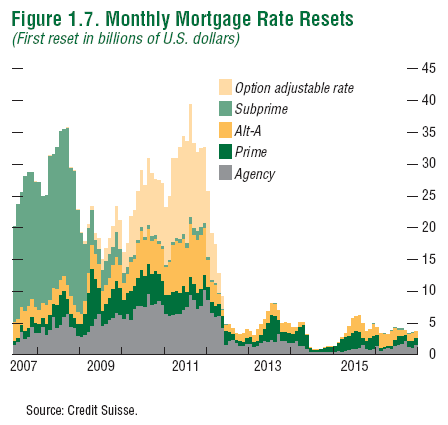
For example, a RM 200,000 loan with tenure of 20 years, the initial repayment can be as low as RM 800 a month. When the 3-5 years period expires, the loan will be automatically resets to higher interest rates, probably (BLR + 0%) and repayment will be more than RM 1000 per month. One thing to remember is that ARMs is one of the major contributors to the U.S Housing meltdown. The following is the U.S Monthly Mortgage Rate Resets.
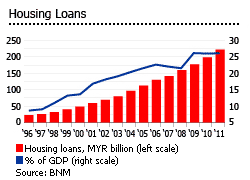
As can be seen above, the U.S housing crisis is yet to be over as the mortgage resets will continue beyond the year 2015. As for Malaysia our total housing loans has risen to MYR 222.2 billion from about MYR 25 billion in 1996.
Below is the chart for the housing loans to GDP as from 1996 to 2011.

It shows that the outstanding housing loans has been on the rise since 1996 and reached MYR 222.2 billion in 2011 or around 26.1% of GDP, up 11.8% from a year earlier.
An oversupply of Housing?
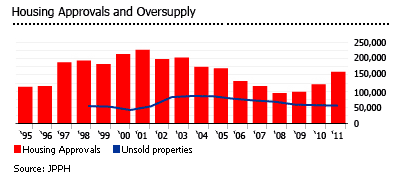
According to C.H. Williams Talhar & Wong, there is an oversupply of high-end condominiums in Malaysia especially in Kuala Lumpur, Johor Bahru, Kota Kinabalu, Kuching and Penang. The following chart shows the relationship between the housing approval and oversupply.
The over-supply of high-end condominiums remains a concern while a further 2,300 units of high-end condominiums will be completed in 2012, half located in the Kuala Lumpur City Centre (KLCC).
In total, around 54,557 properties were unsold at end-2011, down 2.3% on the previous year, and down 34.9% from the 2004 peak of 83,811 units. There was a 62.3% decline in house launches during the year to Q4 2011. It clearly shows that the housing market is already softening since the end of 2011. Moreover, we also received reports from real estate agents complaining that high-end properties (over MYR 1 million) are very sticky or difficult to sell.
Bank Negara Malaysia’s new measures
We are certainly living in interesting times. Fundamentally, our economy is weak. Our exports are plunging, our trade balances and deficits are negative and the only things that are going up are our companies bankruptcy that is on record territory, stock market, consumer spending, inflation, private and public debts. It seems like things are moving in opposite directions. Positive economic indicators are moving down while negative economic indicators such as inflation and household debts are moving up.
In view of our credit expansion problems, Bank Negara Malaysia (Central Bank of Malaysia) is implementing the following measures to curb the excessive debt incurred on the private sector namely the Household and Housing sector with immediate effect (06/07/2013).
> Reducing tenure of housing loans from 45 to 35 years
> Limiting tenure of personal loans to the maximum of 10 years.
> Prohibition of offering pre-approved personal financing products.
Before we address the effects of the above measures, we would like to digest what Bank Negara hoped to achieve with the above measures. In short, Bank Negara is trying to reduce the banking sector’s exposure to real estate and personal loans. In trying to do so, it is employing a strategy known as ‘shortening of maturities’. This can be literally translated in plain English as ‘the government is more concerned with short term instability than promoting long term growth’. In part, these measures we believe are also directed towards resolving our big budget deficits and Government Debt to GDP problem. Again these problems are due to our excesses in the past few years of credit expansion.
So how will the Government going to fix this problem? Our Government hoped that by reducing the credit, it will help reduce domestic consumption on consumer goods and real estate and at the same time try to expand the exports. This in time will helped reduce the trade balance due to the increase in exports and decrease in imports. By this our Government hoped to help built a sounder economy with a better income foundation and lesser debts.
However along the way a lot of people are going to get hurt due to the credit squeeze but there is no other choice if we want a transition to a better and more sustainable economy. Hopefully, more resources will be directed towards the more efficient part of the economy such as building more plants, better infrastructure, modernising production facilities or anything that can help the economy to make real products which can be used for domestic consumption or exports which will in turn earn foreign exchange. Our next question is will it work?
Will it work?
It appears that Bank Negara is definitely worried on the banking sector’s exposure to real estate. Any big downturn in real estate prices will definitely have profound effects on the economy. Among them are unemployment resulted from the construction related business and also the growth of NPLs in the banking sector. Below are the problems that may arise as a result of the latest measures.
Limitations to Monetary Policy – Long Lag
Central Banks have always been prudent in their approach towards the economy and that is the main problem. Sometime they waited too long before they act or when the problem is evidently long in its tooth. The slow response may be due to the problems associated with monetary policy implementation and they are the long-lag response and genie out of the bottle response. Monetary policy such as increasing the interest rate to counter inflationary pressure might take 6-9 months to work its way into the economy. If they waited until the inflationary effect is visible to us then it is already too late because the inflationary effect has already accelerated too much and the interest rate increase will have not much effect in contracting the economy.
Similarly to what is happening in Malaysia. Bank Negara should have taken action many months ago to stem the borrowing to the private sector and not waited until the problem becomes obvious. Now when they starting to take action, the genie is already out of the bottle and it is all but one hell of a difficult task to stuff the genie back into the bottle. The above measures will only have effects on new loans, how about the old ones?
Problem with our Shadow Banking System
This I would like to point out that as in many other countries we also have two different banking systems. One is called the formal banking where their operations are regulated by Bank Negara and the other one is the informal banking which is unregulated by Bank Negara. The informal banking system or Shadow Banking System consists of lending from private money lender and credit companies, inter-company loans, corporate bonds and loans by investment companies
Due to the current credit squeeze those who are unable to qualify for loans in the formal banks will turn to the informal banks. There are already a lot of evidence of individuals and SMEs and even developers are getting loans from the informal banks where maturities are short and interest rates are high. The problem is we do not know how large our informal banks are and what type of portfolios they are holding. Another problem is we do not know what sort of linkage or relationship between the formal and informal banks. If they are linked and if our real estate market were to collapse then the resulted decline in real estate prices will be serious, due to the following.
There will be force sales of real estate financed by the informal banks. This self-reinforce selling will further depress the prices of real estate. This is the last thing our Government wants because when the informal banks start to liquidate their assets to raise cash then it will cause further downward pressure on the market.
Informal banks may have got their funding from the formal banks. So any credit squeeze will certainly have effect on the operations of the informal banks which might force them to shorten the maturities, recall or totally freeze their loan operations.
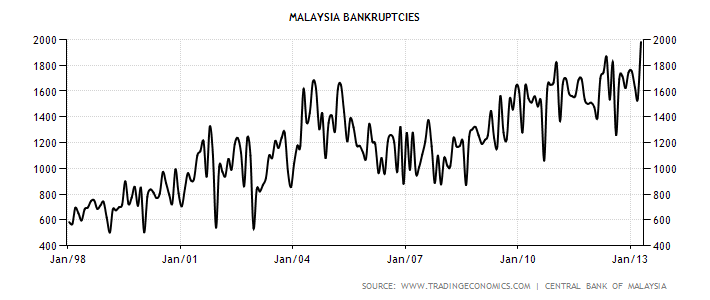
Without funds to finance their operations, many businesses may have to cease their operations. With the expected softening of the real estate market developers who have been snapping up land to build up their land banks will find it difficult to stay afloat. This can be shown with the following chart on bankruptcies in Malaysia from April 2011 to May 2013.
As from the two charts above, Malaysia recorded an increase in company bankruptcy. Total company bankruptcies reached a high of 1981 companies in April 2013. This is the highest ever number of bankruptcies recorded since January 1998. In view of the credit crunch we expect to see much more bankruptcies in the month ahead.
Hence, such risk is real and is already happening. Credit squeeze means there will be lack of funds available to individuals and companies and hence liquidity. Since liquidity is the lifeline of both the housing and stock market, a lack of it will definitely have profound effects on them. Lacked of liquidity will cause seizing up of transactions because of the negative expectations on the economy will make people and businesses lee willing to spend, which eventually will drive prices down. Even before the implementation of the credit squeeze the housing market has already shown signs of weakness.
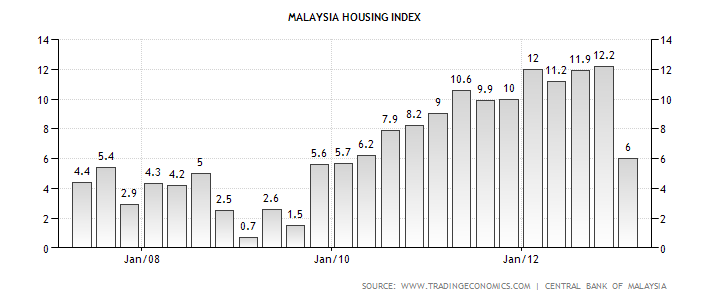
The Housing index refers to the residential construction activity during a period of time. As indicated by the housing index below, our residential construction activity has declined to 6% in the first quarter of 2013 from 12.2% recorded in the last quarter of 2012. It represents more than a 50% drop on a quarter to quarter basis. At 6% it brings us back to the level recorded in the early 2010 when our economy is just started to recover from the Global Financial Crisis in 2008. This big drop in housing activity certainly worries the authorities and which might be attributed to the over-leveraged consumers and also the peaking of the housing prices.
Housing prices in Tier-1 cities in Malaysia namely Kuala Lumpur, Penang and Johor Bahru has seen an unprecedented rise due to the easy availability of credit that resulted in a speculative frenzy. Any investment that is buoyed by easy credit especially housing and the stock market will eventually end up in a bubble. Despite numerous denials by our authorities the housing market in Malaysia has long been in a bubble.

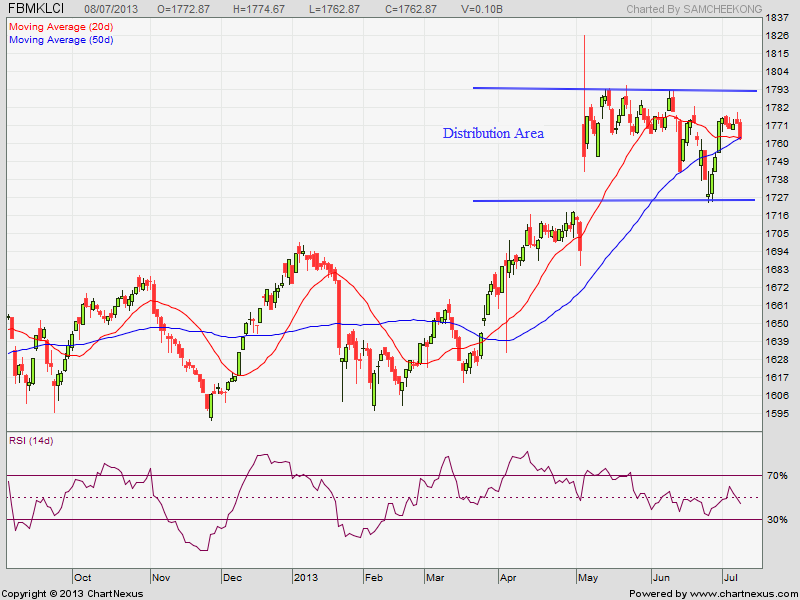
As for the Stock Market we are saying it again. Sell and walk away. From the chart the market has been on the Distribution phase since 05/05/2013. We have drawn two lines that represent the distribution area and we will expect the market to breakdown from the lower line in the coming weeks. By then you will see an extremely volatile market.

Due to the credit contraction we are expecting a continuation of decline into the next few months. Any rebound will be another bear trap and we are seeing a much lower index in the next few weeks and month. In short we are BEARISH!

Sunday, May 5, 2013

Warren Buffett's wisdom goes a long way

Warren Buffett offers advice on investing and life

  Billionaire Warren Buffett dispensed plenty of advice on investing and life during this weekend's Berkshire Hathaway shareholders meeting.

The wisdom Buffett and his investing partner Charlie Munger offer is part of what attracts more than 30,000 to the meetings each year.
Here's a sample of their insights:
INVESTING SUCCESS:
Buffett and Munger told shareholders that successful investors must learn all they can about the businesses they are buying and stick to industries they know, but the right temperament is also important.
"You just have to avoid getting excited when other people are excited," Buffett said.
Admittedly, it's hard to continue to make rational decisions about investments when the stock market is soaring, but it has proven profitable for Berkshire Hathaway.
"We've always tried to stay sane when other people like to go crazy," Munger said. "That's a competitive advantage."


The above appears in Yahoo news.on 6th May 2013
Must learn from him to be successful.

Friday, March 15, 2013

Next week at KLSE by Dr.Nazri


Bursa to continue downside next week


KUALA LUMPUR -- Bursa Malaysia is expected to continue its downside next week, dampened by the investors' wait-and-see attitude, profit-taking and traders' caution ahead of 13th general elections (GE13).

 Affin Investment Bank head of retail research, Dr Nazri Khan, said the local bourse, which was expected to touch the 1,620 level, however, will see moderate bargain hunting, especially among property and plantation counters.
 "Hence, we expect the local sentiment to be cautiously volatile, with alternating up and down FBM KLCI swings, ahead of the impending dissolution of parliament, which should be weeks away to pave the way for GE13. 
 "Further, the strength in the US dollar, softer ringgit and weaker commodities are another drags capping local equity upside," he told Bernama.
   Nazri said buying momentum and market breadth remained weak with the KLCI sliding 1.5 per cent from last week's high of 1664.39.
   He said based on historical trends, any downside and weakness weeks before GE were good buying opportunities. 
 "The FBM KLCI will generally soften before the general election, stabilise immediately after and hit a new high within three months after the election," hesaid.
   Although many investors were adopting a wait-and-see attitude currently,Nazri said, now was the best time to invest in quality local blue-chips. 
 "We expect most investors, especially foreign and high-end retail, to jumpback into the stock market immediately after the elections, pushing the local bourse higher in the early second half this year. 
 "We also see impressive strengths in our regional neighbours' stocks, which means Bursa Malaysia will play strong catch-up post-election," he said.
   Malaysia's better-than-expected fourth quarter 2012 gross domestic productgrowth and the expected resilient in the 2013 first quarter's earning resultsshould continue to support further upward revisions and higher stock price post-election, Nazri said.
 "Based on these resilient fundamentals, we are pegging 1,720 as our AffinInvestment Bank official target (post-GE) for the FBM KLCI by year-end which again means that now is an opportune time to accumulate stocks," he said.  - Bernama


Thursday, January 3, 2013

Important lessons to understand the stock market

Emotions can adversely influence our investment decisions and lead to irrational behaviour, according to a new study by Franklin Templeton Investments.
Many a time, one's emotional response is so instantaneous that one is unaware it is even occurring. And experts say a small little part of our brain called the amygdala may play a key role in our bad decisions.
It functions as the brain's early warning system, sending out messages of fear and anxiety to raise the alert of imminent trouble. This may cause us to regard negativity and pessimism as accurate.Understanding our emotional state and putting plans in place before emotions take over can help prevent poor investment decisions. The Franklin Templeton Investments report found five common mistakes made by investors, which can be easily avoided:

Loss aversion

This refers to the deep pain investors feel upon taking a loss and the lengths to which they will go to avoid that pain.
A study by psychologists Daniel Kahneman and Amos Tversky found that between a certain loss of US$3,000 (S$3,675), and an 80 per cent chance of losing US$4,000 and 20 per cent chance of losing nothing, more than 90 per cent of investors polled picked the latter, even though statistically it was the riskier proposition.
Since the global financial crisis- led market meltdown in 2008, many investors have been reluctant to buy equities out of loss aversion. They have preferred to remain in low-yielding vehicles that may deliver a negative real return after inflation.

Holding on to the past

Stock markets reflect the tendency of investors to anchor expectations to a given price. For example, a stock will typically trade for a while within a given range, then trend up or down to a new anchor level and trade within that new range.
Investors adjust expectations to the altered price, which is why overly sharp gains or losses provoke discomfort.
The sensitivity shown to price changes may be largely the result of memory for prices paid in the past, and not at all a reflection of true preferences or level of demand.

Following the crowd

A modern example of how the herd mentality can go seriously wrong is the dot.com phenomenon of 2000.
While the significance of the Internet was real and enduring, many of the companies into which investors poured their money were neither.
So, following the crowd can be a precursor to market bubbles, as what begins as a natural inclination to join in the growth path of a company can end in losses as the euphoria of explosive price increases causes investors to lose their sense of judgment.

Availability bias

Rather than analysing all the relevant information, investors tend to rely on whatever data is most recent or emotionally charged.
This can cause them to overreact to market conditions, whether positive or negative, or invest in a stock simply because it has been heavily covered by the media.

Mental accounting

Many investors practise mental accounting when they lock in certain assets for retirement, maintaining somewhat greater liquidity for controlled wealth accumulation, or allocating a smaller sum for high risk-high reward investments.
However, this compartmentalising means investors may also take unwarranted risks with their own money, or may be overly cautious with an inheritance.


Tuesday, December 25, 2012

The STAR most probably will shine again.

This counter Star (stock code 6084) is currently very weak. Will it shine again? Chances are good a profit will be made if we were to buy at RM 2.60 level.( My personal opinion only)

§  From a 3-month high of RM3.26 (19 sep), STAR tumbled 21% to a low of RM2.58 (24 Dec).
§  Values are likely to resurface after recent plunge and we see limited scope for further significant selldown due to its extremely oversold positions (daily RSI at 6.6 and slow stochastic at 1.8), defensiveness, strong netcash of RM230m as at 3Q12 (or 31sen/share) and attractive net dividends (6.9%). Valuation remains undemanding at 10.7x FTY13 P/E, implying a 11.5% discount to its 5-year average of 12.1x.
§  Immediate supports are RM2.54 (daily lower Bollinger band) and RM2.46 (23.6% FR). Lower supports are RM2.30-2.35. Risk takers may start to nibble as a relief rally in the pipeline with initial upside targets at RM2.72 (100-d SMA) and RM2.83 (20-d SMA). More formidable resistances are RM2.90 (50% FR) and RM3.05 (61.8% FR). Cut loss below RM2.43.

As Warren Buffett once said, be brave when you see blood in the street. There is no blood in the street yet but this particular counter (Star) has blood all over its price. So maybe it is good to buy some at around RM2.60 and sell when there is resonable profit to be made. 

Friday, August 31, 2012

Genting Malaysia ... Update

This is just an update on Genting Malaysia (4715) since my last posting on 13 August 2012, and it seems that it is on track and about to enter very crucial stage.
There is a strong upthick on the last trading day Thursday ( 30th August 2012) before the market close for the National Day holiday. 
The price of Genting Malaysia is about to enter the ichimoku cloud hanging above. Once it penetrates the cloud it will face a resistance at around RM3.60. Those in the trading of shares may consider selling off at this level if he/she has bought it at around RM3.30 level as suggested in my previous posting. If this RM3.60 level is penetrated with volume then it will face a very strong resisitance at RM4.06 as indicated by the horizontal line in the chart. If one is investing in this counter, maybe it is good to hold it a while longer as it is now cum dividend of 3.8 sen less 25% tax and will only be traded ex on 22nd October 2012 which is still quite far away.


Monday, August 13, 2012

I have observed many counters listed in Bursamalaysia currently are having lack luster performance. Can this be an opportunity to bargain hunt? Well, the average PE of the market is actually not cheap right now, so it may not be wise to do serious investment by accumulating for a very long term of 3 to 5 years time frame. 13th General Election is around the corner and this GE13 is very fluid, which will definitely add one uncertainty factor to make many investors worrisome. Having said that, I will think that trading will be a better option now for us to try to make some money. I think Genting Malaysia is one of the many potential counters to buy and try to make some money right now.

   The chart above is taken from Chartnexus for Genting Malaysia. This counter has been on the downtrend since peaking at RM4.05 on 2nd February 2012. Now if you pay attention and look at it carefully it may be just coming out of the bottom at around RM3.30 (at least temporarily)
The following can be observed:-

1. The double bottom at RM3.30 serves a strong support. If this support is violated it may go lower. But it looks unlikely at least for now.

2. Parabolic SAR has given out a bullish sign or what is commonly called a reversal of trend.

3. RSI has gone below 30 and is now cutting abow 30, which is also a reversal signal.

4. MACD is showing a golden cross of blue line (faster line) cutting above the red line (slower line)

5. Similarly, stochastic is also turning up which is a bullish sign.

The horizontal lines I inserted in the chart are roughly the resistance on the way up (if any).
1st resistance is at around RM3.63 and if broken the next resistance will be roughly RM3.79, then RM3.91 and of course the strong resistance ultimately will be the last peak which is RM4.05. And if RM4.05 can be broken with huge volume it may go even higher.

Therefore, it maybe profitable to buy some now and sell higher later for a profit.

** This observation of mine is not to induce you to trade as there is alway risk involved. If you do use my information for whatever purpose the risk is yours. If you  cannot take risk always stay away from stock market **

Wednesday, June 6, 2012

BJToto.. positive development

BJtoto: It is setting up a trust to house its NFO in Malaysia, in a deal that will deliver a bumper dividend and distribution of free units in the trust. Its proposal is to transfer its entire equity interest in Sports Toto Malaysia Sdn Bhd (STM), which holds the lottery license, to a Singapore based business trust to be known as STM Trust.

The proposal will value BJtoto’s Malaysian NFO business at rm6 billion. The rm6 billion consideration for the transfer will be satisfied chiefly by the issuance of 4.43 billion new units of STM Trust. With the STM units in hand, BJtoto will control about 90.59% in the trust before the IPO in Singapore. The balance consideration of about rm528 million will then be satisfied by way of a promissory note in favor of BJtoto.

After the asset transfer, BJtoto will seek to list up to 4.89 billion units of STM Trust on the Main Board of SGX. This is possibly the first trust that is based on NFO assets to list in Singapore.

BJtoto is expected to pocket rm668 million cash from the sale of 540 million units in the listing exercise, based on an offer price of S$0.50 each. The amount could be bigger should the IPO fetch a higher valuation in Singapore.

Under the proposal, BJtoto said it might also consider distributing all or substantial portion of STM Trust to its existing shareholders. In addition it will propose to distribute the net proceeds from the asset restructuring exercise as a special dividend.

Sunday, May 20, 2012

Market Commentaries & Technical Analysis as at 21 May 2012

State Of Global Economic Cycle (May 2012)
Recession – Recovery – Growth/Expansion – Boom – Burst

Investment Strategy (May 2012): Defensive Neutral Aggressive (Domestic News-Flow From May 2012 onwards and Election Theme Play Amid Uncertainties Ahead – Europe’s Sovereign Debt Crisis, High Oil Prices & Inflationary Pressure, Slow US Growth Momentum While China Grapples With Inflationary Pressures and Slow Growth – Have Given Rise To Fears That Global Economy May Stall.

Sectors/Theme To Focus On (21 May – 25 May 2012): News Flow Related and Political Linked Companies.

Stock Market Leading Performance Indicator (21 May 2012 – 25 May 2012)
4 (0-3-Bearish 4-6-Neutral 7-10-Bullish)

The Risks

1.      The Global Economic Recovery Is Precarious (Vulnerable To The Risk Of More Financial Shocks);
2.      Divergent Growth Path of The Two Regions - A Slowdown In Advanced Economies And The Robust Growth In Emerging Markets – Is Posing A Dilemma For Macroeconomic Policymakers In Asia;
3.      Threats Of Asset Bubbles In Asia (Huge Foreign Capital Inflow Of Liquidity);
4.      Volatile Foreign Exchange Market (Currency War) – Competitive Devaluations & US Dollar/Yen Carry Trade (Destabilizing The Global Financial System & Trading Relationships);
5.      Rising Commodities Prices & Threats Of Commodity Inflation;
6.      Inflation Threat In Emerging Ex-Japan Economies;
7.      Fear Of Double-Dip Recession In The US & Eurozone Economies;
8.      Deflation & Stagflation Threat In Developed Economies;
9.      Fear Of A US Dollar Crisis;
10.  Unwinding Of US Dollar/Yen Carry Trade When US Starts To Normalise Rates (Destabilizing The Global Financial System & The Global Economy);
11.  Global Imbalances, Threat Of Trade & Currency War and Protectionism (Destabilizing The Global Economy);
12.  Contagion Effects Of Eurozone Debts Crisis on Other European Sovereign Debt;
13.  US & Europe Debt Crisis: Further Downgrade Of Credit Rating By Rating Agencies

Black Swan Events Or (Unpredictable) Risks/Surprises

1.      Terrorist Attack -
2.      Oil Supply Disruptions -
3.      A Pandemic Disease -
4.      Geomagnetic Storms -
5.      Major Social And Geopolitical Upheaval
6.      Financial Shock – Eurozone Debt Crisis & Disintegrwtion Of EU Bloc Countries

Market Commentaries

It is external factors now (May 2012) driving the market down. Compared to our regional peers, the FBM KLCI has been holding well until recently. So this drop is actually expected, just that Malaysia has a delayed reaction.

Shares on Bursa Malaysia are likely to dip further amid persistent worries over the global economy. Also expect more local bearishness on the weakening ringgit and commodities.

However ample local liquidity and positive local themes such as the upcoming mega flotation exercises like Felda Global Ventures Bhd and impending project news flow such as RM15 billion North Malay Basin will cushion market decline in the near term.

Greece is set to hold fresh elections on June 17, 2012 after voters rejected austerity measures imposed on it by the EU and the IMF, stirring fears that the country would not stick to the austerity measures earlier agreed upon with the European Central Bank and the IMF. The country has put in place a caretaker government but concerns that it will exit the eurozone. Opinion polls show that anti-bailout parties will perform strongly in a new vote next month.

The 13th GE is another dampener on the Malaysian stocks and does not think the market has priced in (May 2012) a negative outcome for the ruling coalition BN.

Meanwhile the easing of interest rates trend will continue in 2012. In an environment of slowing global growth and easing inflationary pressure, emerging markets tend to revert their attention to stimulating economic growth. Governments will also need to formulate appropriate policies to generate employment and address income inequality.

In this slightly uncertain environment, expects Malaysia to under perform even as macroeconomic risks diminish. Thus, the Malaysian stock market may lag its regional peers due to perceived heightened political risks from the imminent general election.

The bearish sentiment was also attributed to growing fears over the eurozone breakup, following the new European politics with anti-austerity parties forming post-election governments.

In US equities market, normally a big decline would set up Wall Street for a technical rebound. But that may not be the case this coming week, even after the market posted its worst weekly loss for the year and the S&P fell for six straight sessions.

With the corporate earnings season drawing to an end and recent U.S. economic data raising doubts about the pace of growth, the S&P 500, which is down 7.3 percent so far in till 18 May 2012, could decline further coming week as concerns about the financial health of Europe persist.

Weighing on sentiment is a growing sense among investors that the euro zone debt crisis is nearing new heights, fueled by fears of the potential for a Greek euro exit and the deteriorating health of the Spanish banking system.

Solid corporate earnings and upbeat U.S. economic indicators had fueled the rally in U.S. stocks, offsetting jitters over Europe. But with earnings almost out of the way and data starting to disappoint, investors have shifted their focus back to headlines out of Europe.

Chartist said that the market is extremely oversold now (18 May 2012). Nonetheless, all major indicators of US market remain on sell signals.

The market remains uncertain on concern that Europe's debt crisis was deepening with the European Central Bank's (ECB) decision to halt lending to Greece banks and Spain following Moody's ratings downgrade of 16 Spanish banks.

With Greece set to run out of money as early as June 2012 and no new government in place to negotiate the next aid installment, investors have begun betting that a chaotic Greek default and euro exit will happen sooner rather than later.

Investors remained fearful that a Greek exit from the euro will increase contagion across the continent's financial system.

However Global central banks stand ready to launch a monetary stimulus package if conditions warrant it as well as further intervention by the ECB to calm markets. Any news by the ECB to engage in direct and large-scale quantitative easing to stem the euro crisis is likely to push the market higher.

Already the ECB had warned Greece that it will not receive any more financial aid if ot does not stick to the agreed bailout deal. The ECB had also gave no indication of intervening in the bond market again any time soon, but it said it was still too early to withdraw the bank’s emergency support measures. The ECB has hardly use of its bond purchase programme since Nov 2011.

Europe remains a key risk factor in influencing global trade amid the danger of a deeper-than-expected recession and the spillover effects to the rest of the world.

European politics will also be ontinued to command the spotlight with more elections looming in several countries. This would result in new leadership changes just as the European continent continue to struggle to resolve the sovereign debt crisis.

Germany’s next federal election is expected to take place between Sept 2013 and Oct 2013. A decline in the eurozone’s fortunes would not augur well for US president Barack Obama’s administration either given the impact it could have on the US economy and US banks holding European debt papers. Obama who is also up for re election for a second and final term as president come Nov 2012, could also win points if his administration helps create more jobs.

The question is how the eurozone debt crisis is going to be and how this would impact Asia especially when the US economy still faces an uncertain recovery.

For US the April 2012 employment report came in weaker than expected, showing that only 115,000 jobs were created during the month. Investors are worried about a repeat of the last two years (2010 – 2011) when stocks peaked in the spring.

The unemployment rate ticked down to 8.1%, but that was because prospective workers dropped out of the job hunt, not because meaningful job growth put people back to work. The April 2012 report marks the third consecutive month of declining job growth. The sad reality is that the jobs market is in for a longer recovery, because the cycle of getting more people employed will be pushed out further until the United States can reach the ideal level of structural unemployment.

And it has more to do with the Fed and the notion that things get bad and Bernanke has said the Fed will be more accommodative. The Fed may come in with the June 2012 meeting maybe and offer the market more accommodation.

Meanwhile investors have been pouting over a U.S. economy that is “not hot enough for a sustained recovery and not cold enough to prompt Bernanke to institute a [third round of quantitative easing].

Amidst the climate of economic uncertainty, there is hope that Asia's emerging markets would escape the worst of the fallout from the troubles affecting Europe and perhaps even the choppy US economic recovery despite recent data showing some improvement.

The hope is that domestic demand driven by a combination of private consumption and fiscal pump-priming by governments would help avert a bumpier ride this year or until the pressures emanating from the end-markets in the developed economies ease off.

Technical Analysis

Bursa Malaysias consolidation process changed for the worse the past week, as external uncertainty came back to haunt investors. In the wake of liquidation, the FBM KLCI dived to a low of 1,526.60 during intra-day session last Friday, resulting in all the gains posted year-to-date being wiped out.

Meanwhile, the selloff had dragged the key index below the 100-day simple moving average (SMA), the first time since mid-December 2011, and also brought about the third dead cross on the chart.

Combined with the growing signs of instability among Spanish banks, the political turmoil in Greece, heightening concerns about a slowdown in China and the latest weak US data adding to the list of risk factors and denting sentiment, it really does not bode well for the market in the immediate term.

Going forward, the 200-day SMA of 1,510 is in great danger. A slip below the 1,500-point psychological level would further damage the mid-term landscape of the local bourse.

Lower support floors are anticipated at 1,480 points, followed by the 1,448 to 1,450-point band and the next, at 1,420-1,424 points range.

Technically, most of the indicators are frail, implying range-bound pattern at best. This may also mean that any rebound is likely to be short-lived, at least for now.

Initial resistance is seen at 1,560 points. The next upper hurdle is resting at the 1,591-point level.


Saturday, April 7, 2012

Sell in May and go away

Last year, the S&P 500 peaked on May 2 at 1,370.58.
By early August, it had dropped nearly 20% and was testing support at 1,100...
It took the S&P until last February 2012 to get back to that 1,370 peak.
In 2010, the S&P 500 hit an intra-day high of 1,219.80 on April 26.
By early July, the index hit an intra-day low of 1,010.91. That was a 17% decline — and it took until November for stocks to regain their April highs.
Yes, since the stock market bottomed on March 9, 2009, the simple “sell in May” strategy has been pretty darned effective.

Tuesday, March 27, 2012

Semiconductor sector remains lackluster

Cautiously Optimistic
§  Worldwide sales remain lackluster: recorded seventh consecutive yoy growth contraction with -8.8% reaching USD23.18bn (3 months moving averages) in January 2012.
§  Slightly optimistic outlook: WSTS foresees the market to grow only at 2.6% and 5.8% in 2012 and 2013 respectively, vis-à-vis to the double-digit growth experienced in 2007 and 2009.
§  Highly correlated: MPI and Unisem’s 2012 and 2013 revenue growth will be dictated by the underlying worldwide semiconductor growth trend.
§  Electronics demand: subdued demand in IT/PC markets due to depressed consumer confident as the result of European debt crisis will be offset by better outlook in both telecommunication and automotive industries.
§  Telco market: main catalyst to the recovery of the industry as cellcos leapfrog into 4G/LTE standard and proliferation of smartphones (especially low-cost models) and tablets.
§  Auto market: Higher production of hybrid and electric cars will spur the industry as more IC components are required.
§  We believe that Moore’s Law will continue to spur growth coupled with potential growth in the electronics market. Hence, we expect Malaysian semiconductor packagers to experience moderate growth in 2012.
§  However, the growth would be dwarfed by intense competition from Taiwanese peers, higher input costs and appreciation of MYR against USD along with challenging economic outlook which will eventually hampers consumer confident.
§  While the sector is not expected to revisit the glory days of double-digit growth as in 2007 and 2009, we initiate coverage on the sector with a Neutral rating:
MPI (Hold; TP: RM3.57)
Unisem (Hold; TP: RM1.48)


By HLIB Research 28 March 2012